Controller
Give financial operations a clearer control narrative.
Explore how ownership, review checkpoints, exceptions and supporting evidence can be organized around cross-functional business workflows. Confirm supported features and integrations during evaluation.
Discuss evaluation context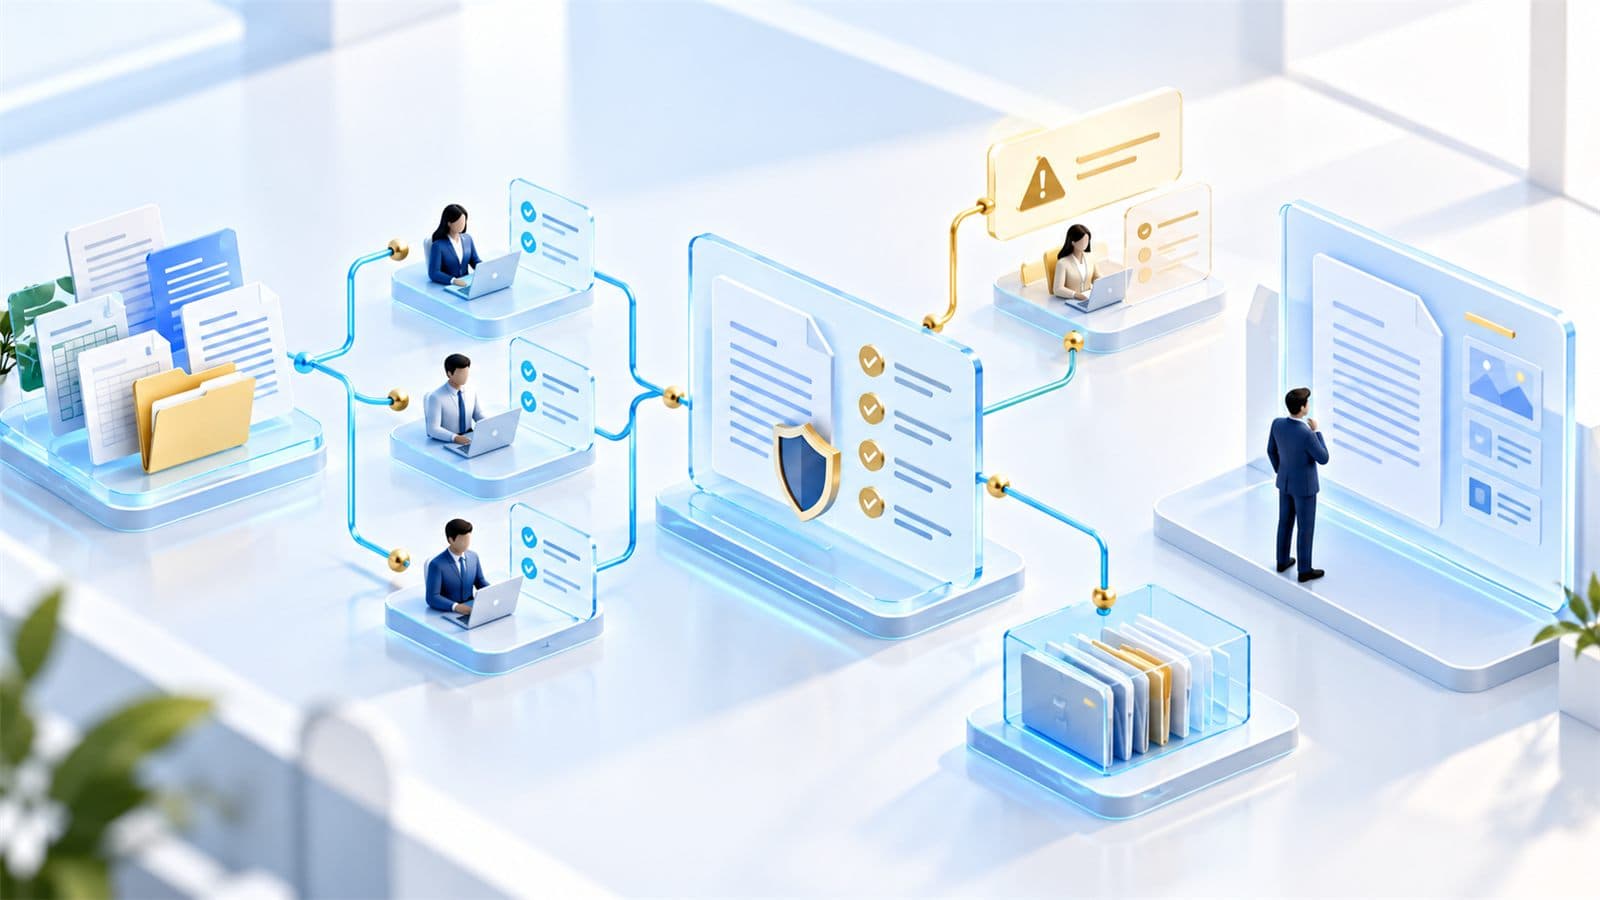
02 / Operating context
Explore the responsibilities behind the decision.
Controller priorities
Three questions to start the review.
Who owns the finance review?
Scope, signal and source context before interpreting a risk.
Who approves the decision?
Accountability, dependencies and decision rights.
What evidence supports the record?
Expected result, verification and unresolved evidence.
Six finance review questions
A clearer financial-control narrative.
D1Financial Process Visibility
Which finance workflows need clearer ownership and status? No automated ledger or real-time feed claim.
- Exceptions / recovery
- Draft / Awaiting input / In review / Returned / Complete / Not available.
- Authority
- Functional process owners, IT/data, Security and applicable policy owners validate real capability and permissions.
D2Review & Approval Accountability
Who signs off, in what order, and what evidence a sign-off actually requires.
D3Exception & Resolution Pathways
How an exception is raised, routed and closed — and who confirms it's closed.
D4Source-System Coordination
Which system is the source of truth for a given figure, and how conflicts between systems are resolved.
D5Evidence & Audit Preparation
What supporting evidence is retained, where it lives, and who can produce it on request.
D6Leadership Reporting & Review
What leadership sees, how often, and what triggers an off-cycle review.
End-to-end concept
A review request, with a blocked path.
- 01
Intake
Identify issue and origin.
- 02
Assess
Scope, impact and uncertainty.
- 03
Assign
Accountable owner and next handoff.
- 04
Approve
Required policy/authorization.
- 05
Execute
Bounded assigned action, not automatic execution.
- 06
Verify
Closure criteria, reviewer and date.
- 07
Review
Retrospective and unresolved follow-up.
Role boundaries
Coordination does not erase authority.
Controller / CFO
Financial review, reconciliation and control narrative; no ERP/ledger automation inferred.
CIO
Source systems, integration and technical access remain IT-owned.
CHRO
Sensitive employee/workforce source authority.
COO
Operating handoffs do not override finance approvals.
Tax / Compliance
Qualified interpretation and legal/regulatory ownership.
Audit / Board
Separate oversight and independent evidence boundaries.
Defining properties
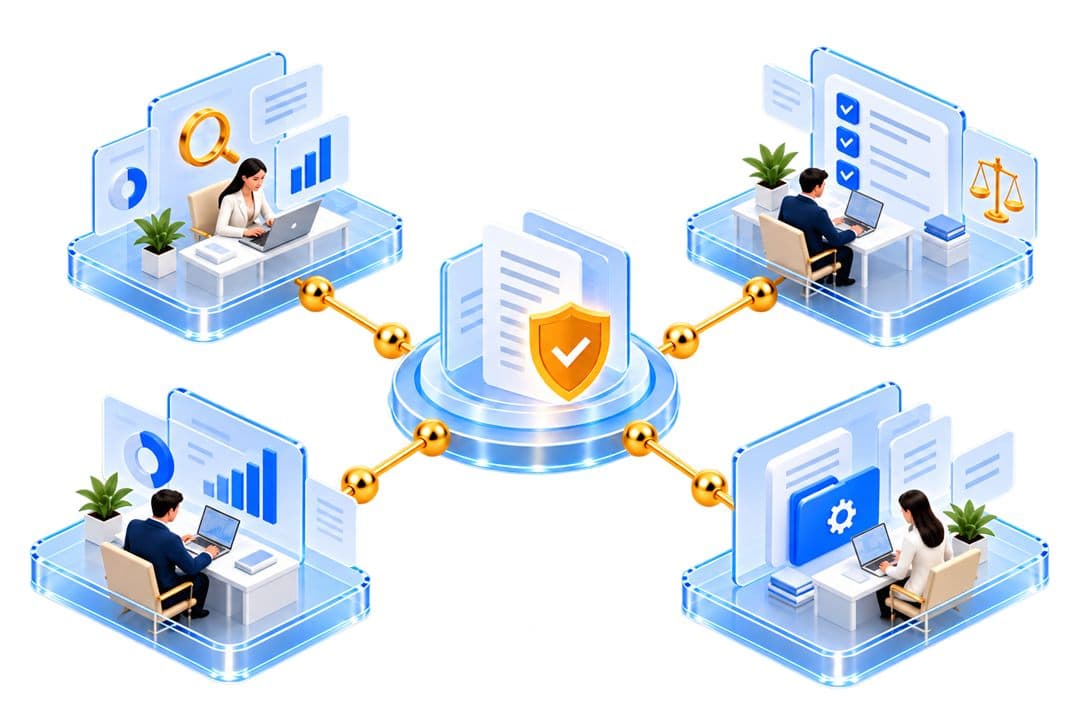
Shared principles. Specialized responsibilities.
Canonical governed-operation properties remain owned by their approved destination; no competing taxonomy is invented here.
Clear answers before evaluation.
Is this live financial software?
No. This page illustrates a concept for discussion; it does not establish live product capability.
Does it automate the ledger or close?
No. No automated ledger, real-time feed, or automatic close is claimed by this overview.
Are specific finance integrations supported?
Any integration needs to be confirmed during evaluation — none are implied here.
Does complete mean audit-approved?
No. Closure under this workflow is distinct from independent audit sign-off.
Can reviewers access all data?
No. Access follows the same role boundaries described above — each role sees only what its function owns.
What happens when evidence is missing?
It is marked as unresolved rather than treated as a false all-clear, consistent with the review pathway above.
Context before conversion
See how this applies to your own governance model.
Discuss the scope, responsibilities and evidence you need. This page illustrates a concept; it does not establish live product capability.
Review evaluation contextLocal briefing preview
Start with one operating decision.
Approved briefing/provider and privacy routes were not supplied. This form sends/stores no information and books no meeting.