Bring clarity to tax responsibilities across the business.
Explore a proposed way to organize tax obligations, decision owners, review checkpoints, exceptions, and supporting evidence across teams and entities.
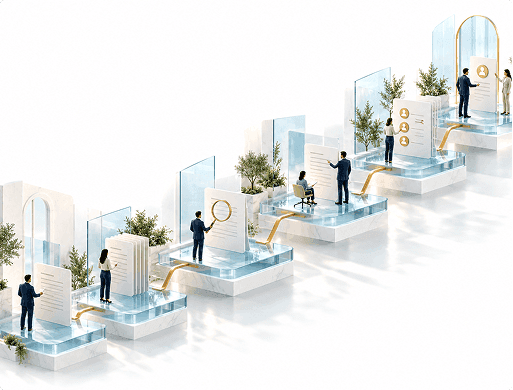
Explore the responsibilities behind the decision.

WHAT THE TAX LADDER MEANS
A progression of responsibilities.
Not a compliance score.
Tax Ladder describes proposed internal governance stages. It is not a statutory tax hierarchy, filing engine, or alternative to qualified tax advice.
Understand the scope
Define the entity, period, and jurisdiction before assigning responsibility.
Coordinate accountability
Connect preparers, reviewers, and decision owners through clear responsibilities.
Prepare for oversight
Keep supporting evidence, gaps, and review context visible to authorized readers.
SCOPE, OWNERSHIP & REVIEW
Keep the source
beside the step.
Explore how a responsibility might be scoped, assigned, reviewed, escalated, documented, and summarized. These are conceptual examples with unverified sample states.
Dates, obligations, and applicability require authoritative sources. Unknown information stays visible.
How the responsibility works
Understand which entity, jurisdiction, reporting period, and obligation category a responsibility belongs to.
Coverage and statutory applicability need confirmation for each scope.
EVIDENCE IS NOT CERTAINTY
A completed task
is not verified compliance.
Keep obligations, assignment, control mapping, exception handling, and supporting evidence separately connected and reviewed.
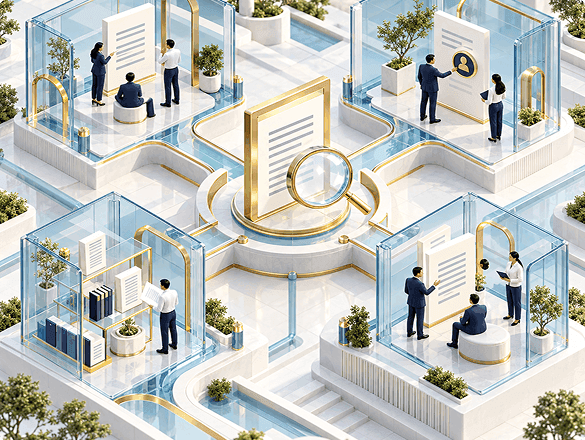
Source and scope
Authoritative source, entity, jurisdiction, and reporting period.
Owner and review
Preparation, independent review, and explicitly delegated approval.
Evidence and oversight
Authorized artifacts, unresolved decisions, and source freshness.
EXPLICIT STATES
Unknown stays unknown.
A missing source, unassigned decision, or restricted scope needs a clear explanation. It must not appear as verified completion.
Not assessed / In review
Missing assessment remains visible. Review is a process state, not an assurance result.
Awaiting owner / Action required
An unresolved decision or gap needs explicit ownership and a next step.
Stale / Source unavailable
Missing or outdated source information cannot support verified due-state judgments.
Restricted / Out of scope
Access restrictions and unsupported scope must remain clear rather than appearing as an empty result.
RESPONSIBILITIES BY PERSPECTIVE
Different readers.
Different responsibilities.
Tax leadership
Understand scoped obligations, jurisdiction context, and review priorities.
Finance / Controller
Connect tax responsibilities with financial reconciliation and supporting evidence.
Compliance leadership
Review policy framing, exceptions, and governance boundaries.
CIO / IT
Assess security, system connectivity, and data lineage requirements.
COO / Operations
Identify process handoffs, bottlenecks, and escalation responsibilities.
Audit committee / Board
Review authorized summaries and unresolved issues at an oversight level.
SOURCE & TRUST
Governance clarity without overclaim.
No universal coverage
Jurisdictions, entities, and obligation applicability require scope-specific confirmation.
No evidence guarantee
Evidence records do not establish legal compliance, certification, or audit approval.
Sensitive records
Do not send tax identifiers, employee tax data, payroll records, or confidential financial artifacts through this page.
No automated tax advice
Calculation, filing, payment, regulatory updates, and professional advice are not established by the supplied sources.
RELATED RESPONSIBILITIES
One responsibility, one authoritative owner.
Keep tax responsibility distinct from financial controls, enterprise compliance, systems administration, and executive oversight.
Tax Ladder
Tax-specific responsibility, ownership, review, exceptions, and evidence concepts.
Controller
Financial reconciliation and internal controls; general ledger and close remain separate.
Compliance Ladder
Broader enterprise compliance governance; shared contracts require Product approval.
CIO / CHRO / COO
System lineage, lawful workforce context, and operating-process responsibilities.
Audit Committee / Board
Authorized evidence questions and aggregate oversight, without routine task assignment.
Defining Properties
Map responsibilities to approved defining properties only after taxonomy validation.
ANSWER-FIRST GUIDANCE
Know the limits before evaluating.
DISCUSS ENTERPRISE EVALUATION
See how this applies to your own governance model.
Discuss scope, responsibilities, and evidence needs. Confirm what is conceptual, what is available, and what requires professional review.
LOCAL EVALUATION PREVIEW
Start with a governance question.
Share general scope, decision ownership, and review needs. Tax Ladder describes a proposed operating model, available capabilities and jurisdiction coverage need confirmation.
Open the Enterprise Sales local page